
An unforeseen emergency room visit or medical procedure in the United States can quickly generate tens of thousands of dollars in medical debt, pushing newly arrived immigrant households into financial distress. Mastering the mechanics of health insurance—including monthly premiums, deductibles, copayments, coinsurance, and out-of-pocket maximum thresholds—is fundamental to safeguarding family health and generational assets.
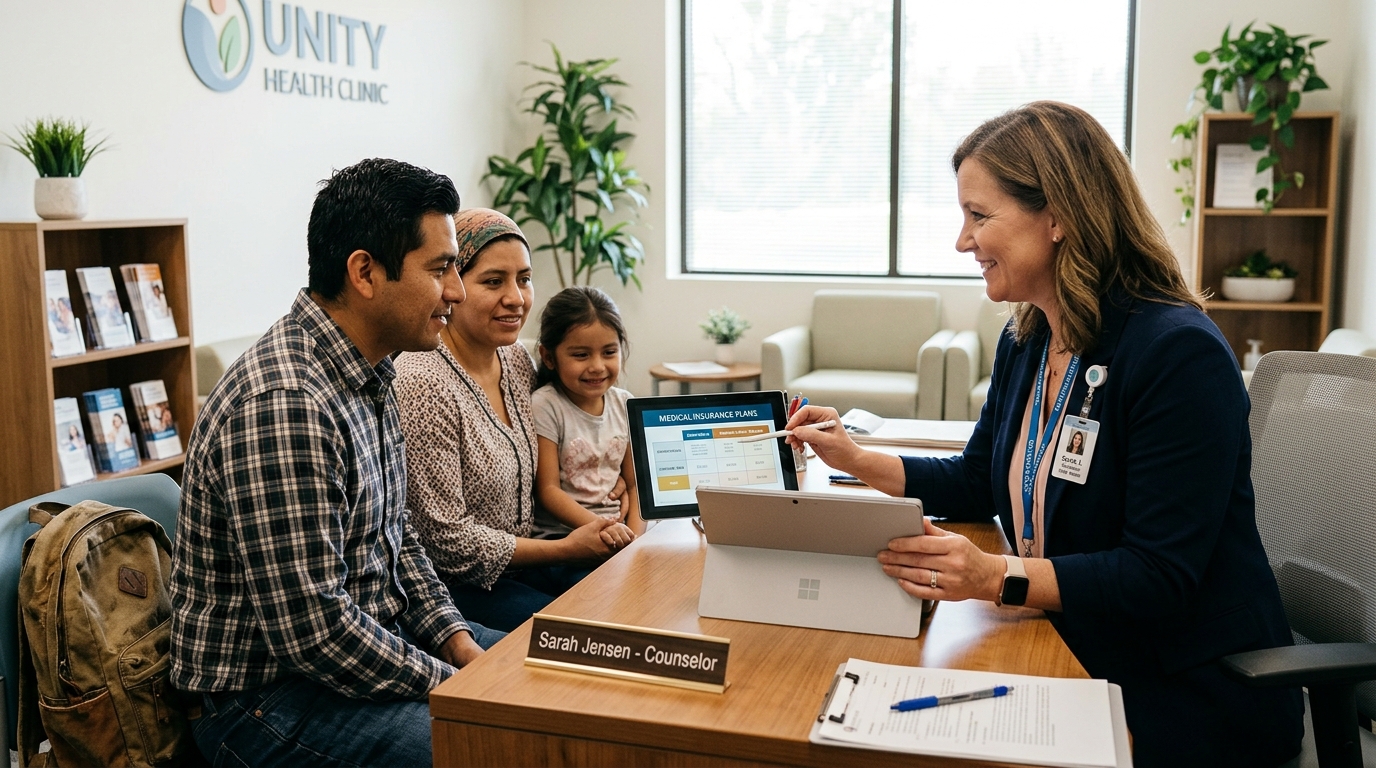
“Misconceptions surrounding the Public Charge rule persistently deter immigrant families from necessary medical care. USCIS policy explicitly affirms that private health plans, ACA marketplace subsidies, and community clinic care do not trigger immigration penalties.”
— Dr. Sarah Jensen, Healthcare Navigator Director / Unity Health Network
The ACA Marketplace (Obamacare) and Premium Tax Credits
Lawfully present immigrants—including permanent residents, employment visa holders, asylees, DACA recipients, and TPS beneficiaries—are eligible to purchase qualified health plans through HealthCare.gov or state-based exchanges. Based on annual household income, enrollees can access Advanced Premium Tax Credits (APTC), significantly lowering monthly out-of-pocket costs for Silver and Gold benchmark policies.
Visitor Health Coverage and Federally Qualified Health Centers (FQHCs)
Individuals holding non-immigrant visas or navigating transitional statuses can obtain comprehensive travel medical insurance plans designed to shield against acute conditions. Concurrently, Federally Qualified Health Centers (FQHCs) deliver primary care, laboratory testing, and dental services on a sliding-fee scale determined strictly by household income, without inquiring about legal status.


